
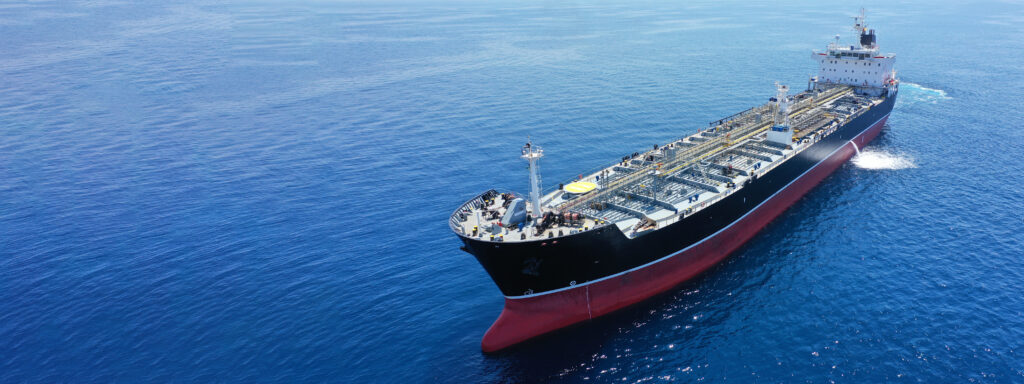
Suezmax and Aframax earnings strengthened further in September, while remarkable resale prices showed the premium buyers are willing to pay for immediate delivery. We expect recovering oil exports and inventory rebuilding to support a strong market beyond a reopening of Hormuz.
Recovering oil flows keeps the fleet under pressure
September showed how the recovery of Gulf oil exports can add to tanker demand even while passage through Hormuz remains restricted. Cargoes moving through the Strait are transferred to other tankers in the Gulf of Oman, requiring separate ships for the shuttle and onward voyage. Reuters reported that transfers were taking nearly ten days by late September, compared with five to seven days previously, as equipment and support services struggled to keep pace. The additional time ties up vessels that would otherwise be available for new cargo.
With many VLCCs committed to these operations, charterers increasingly turned to Suezmaxes and Aframaxes, including for longer voyages from the Atlantic Basin. Suezmax spot earnings reached approximately USD 375,000 per day on 18 September and remained around USD 360,000 a week later. Aframax earnings rose 37% in the final reported week of the month to approximately USD 251,000 per day. The strength also carried into period contracts: one-year Suezmax rates reached USD 145,000 per day, nearly four times their 2025 average, while Aframax rates reached USD 105,000 per day against approximately USD 34,000 last year. For owners securing these contracts, the benefit extends beyond the current spot market.
Buyers pay newbuilding prices for ships available today
TradeWinds reported the sale of a 17-year-old Suezmax for USD 90 million, approximately the price of a newbuilding. The 2017-built Suezmax Speedway reportedly sold for around USD 99 million. These prices reflect the value of earning today’s rates rather than waiting several years for a new vessel.
An eventual reopening of Hormuz would shorten some voyages and release ships from transfer operations, creating scope for rates to ease. However, it would also restore Gulf export volumes and allow depleted inventories to be rebuilt. BRS Shipbrokers estimates that restocking could generate more than 1.7 billion barrels of additional cargo demand across 2027 and 2028 and expects parts of the shuttle system to remain after normal passage resumes. With much of the newly ordered VLCC and Suezmax tonnage only arriving from 2028, the fleet has limited capacity to respond in the near term. We therefore remain positive on the tanker market into 2027, while expecting rates to fluctuate as trade routes adjust.
Sources: BRS Shipbrokers, Clarksons, Reuters & TradeWinds