
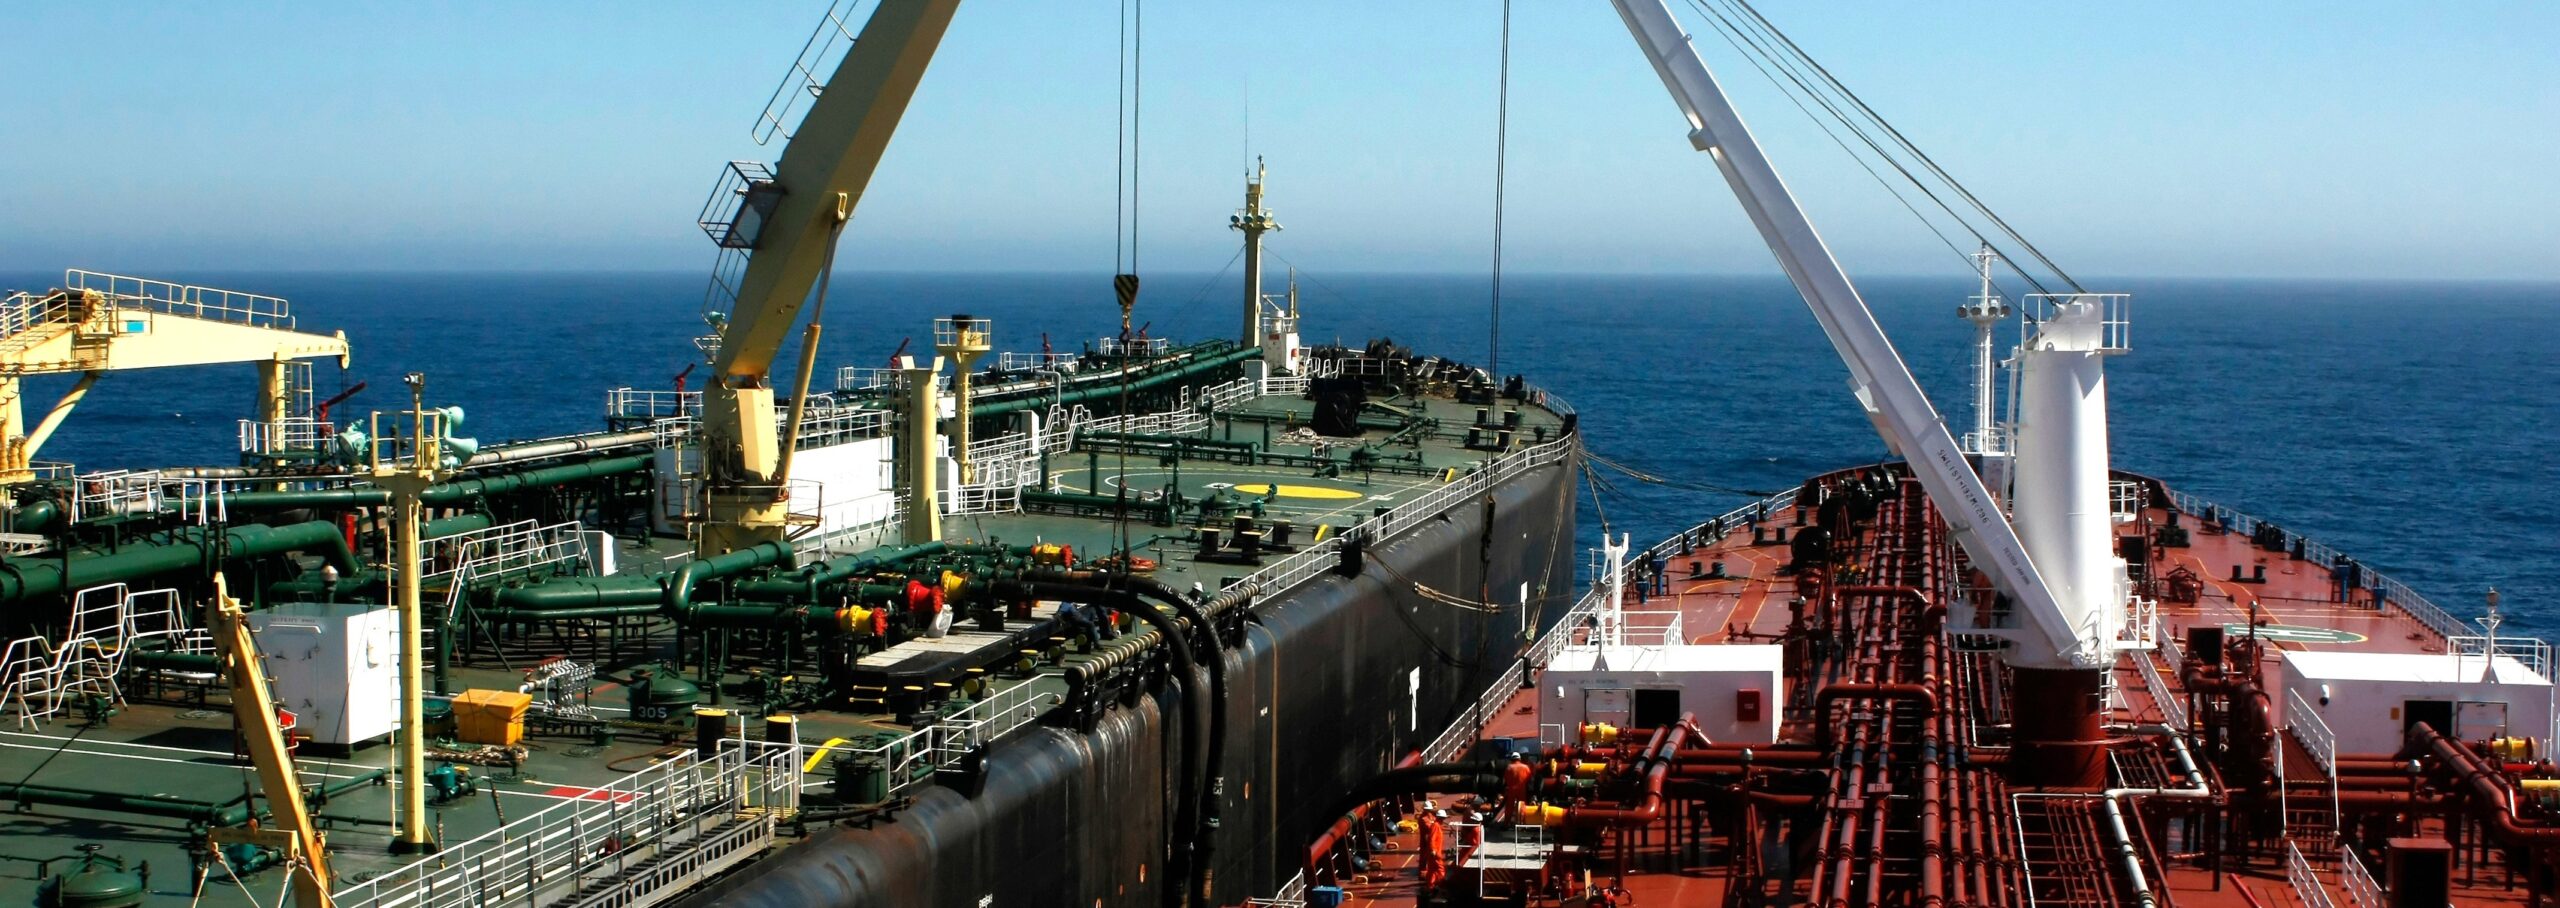
More crude is reaching buyers, but shuttle voyages, offshore transfers and cargo splitting keep vessel capacity under pressure.
Exports have recovered, but shipping remains constrained
Gulf crude and product exports, excluding Iran, reached approximately 16.5 million barrels/day in September, matching pre-war levels and recovering from around 6 million in March, according to Kpler. However, the recovery includes bypass routes, with flows through Hormuz itself still below normal.
Tanker earnings remain exceptional. In the week ending 2 October, VLCC earnings averaged approximately USD 672,000/day, while Suezmax earnings rose 72% to USD 628,000/day and Aframax earnings increased 8% to USD 272,000/day. Recovering exports have therefore not brought a return to normal freight rates.
The answer lies in how crude reaches buyers
Producers have restored exports using bypass pipelines and a shuttle system. Tankers load inside the Gulf, cross Hormuz and transfer crude to other vessels outside the Strait for onward delivery. Cargoes that previously travelled directly to buyers now require multiple ships and additional handling.
Transfers add waiting time, while longer voyages from Atlantic suppliers to Asia keep vessels occupied elsewhere. As exports recover, more cargoes move through this less efficient system, sustaining demand for tanker capacity.
The pressure spreads across vessel sizes. Charterers split larger crude cargoes onto Suezmaxes and Aframaxes, while larger product cargoes are divided among smaller tankers. Average clean MR earnings rose 30% last week to approximately USD 64,000/day, double their early September level.
What to watch
Tanker earnings remain strong because recovering volumes still require more shipping capacity to reach buyers. Rates are likely to remain supported while shuttle operations, transfers and longer voyages continue to absorb vessels. A sustained return to direct voyages through Hormuz, shorter waiting times and more owners willing to enter the region would signal easing pressure on capacity.
Sources: BRS Shipbrokers, Clarksons Research, Kpler & MB Shipbrokers